Illustrative image.
After a coastal hurricane hits a motel corridor, carriers rarely dispute obvious roof openings. Claims stall on hidden interior moisture: rusted packaged terminal air conditioners, black mold behind vanity mirrors, and delaminated wallboard that appears intact until room-by-room tear-out begins.
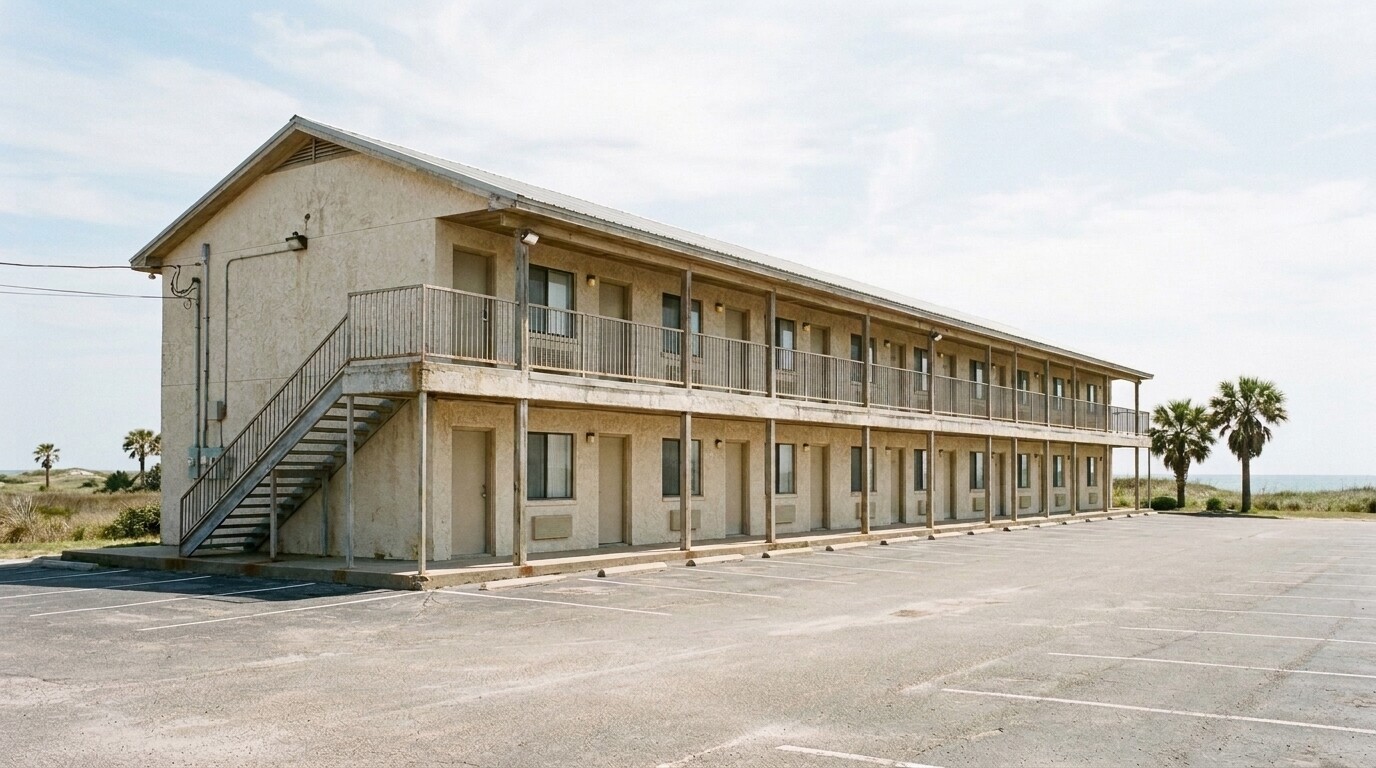
Walking Blue Wave Inn, a two-story exterior-corridor motel on the Texas Coastal Bend, alongside multi-property Gulf Coast storm inspections produced a line-by-line claim matrix spanning the front office and 29 audited guestrooms across three wing numbering blocks.
Evidence Standards That Move Carrier Adjustments
Rough lump-sum repair estimates invite carrier depreciation disputes. Building a defensible adjustment file requires granular physical documentation:
- Logged 885 sequentially numbered inspection photographs mapped directly to individual unit tags from the front office through third-wing double-queen rooms.
- Separated temporary stabilization items, such as plywood-boarded window openings and ceiling patches, from permanent envelope remediation where framing had already begun rotting beneath saturated sills.
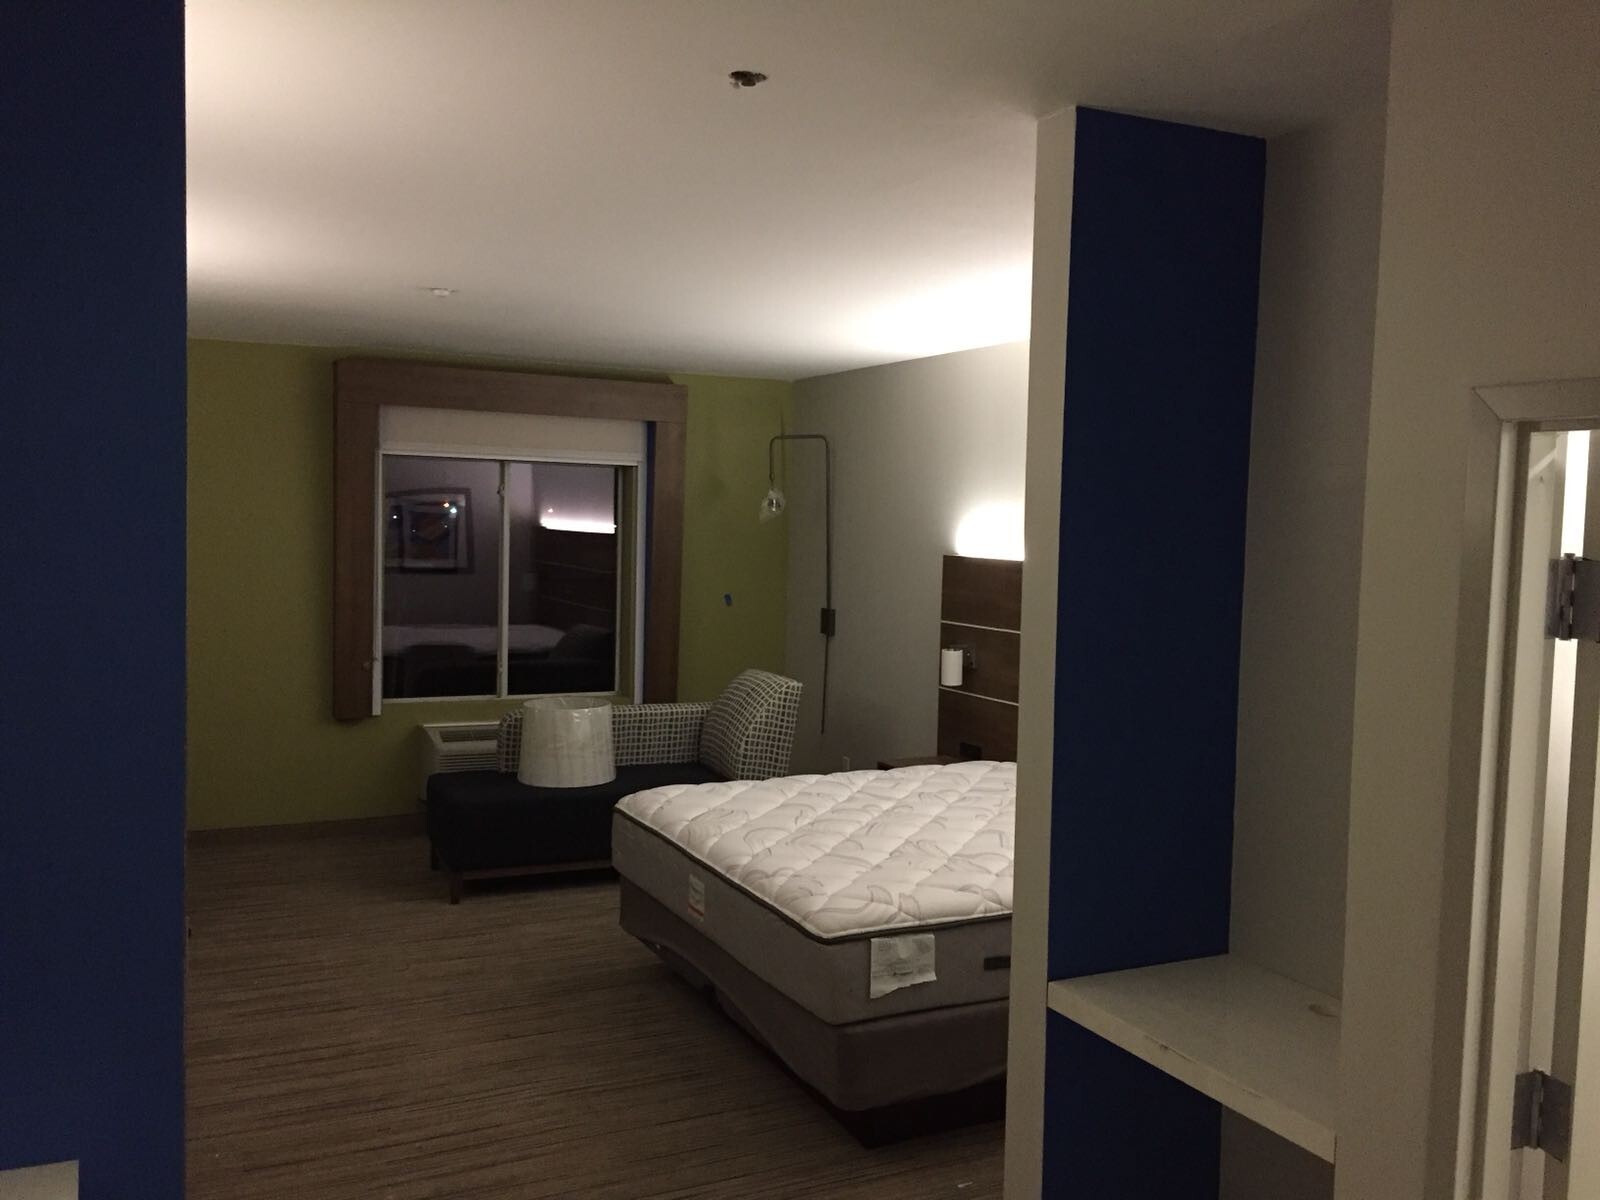
- Documented mechanical deterioration unit by unit, isolating 9,000-BTU PTAC sleeves pulling loose from corroded exterior frames alongside rusted light fixtures and swollen headboard millwork.
Catching Secondary Mold & Framing Failure
Even in rooms that escaped direct roof breaches, wind-driven rain and extended power loss created secondary damage lines that estimators frequently miss:
- Pulled bathroom mirrors and vanity bases off perimeter partitions to record mold growth behind backing boards before drywall demolition crews arrived.
- Flagged peeling paint, splitting closet wallboard, and delaminated door frames caused by high indoor humidity rather than standing floodwater.
The Takeaway
Insurance recovery on a storm-damaged hospitality asset depends on photographic indexing down to the fixture level. When every rusted PTAC unit, rotted stud bay, and mold-compromised mirror sits tied to a numbered room line and photo range, carrier negotiations stay grounded in physical proof.