Buying a flagged economy hotel for a brand conversion looks straightforward on a broker flyer until the lender's capital markets checklist arrives. Without line-by-line franchise termination accounting, realistic FF&E reserves, and three-year trailing and forward budgets, financing dies in underwriting.
On an acquisition and brand-conversion project in Greater DFW, TX, we structured the complete transaction and capital markets diligence file around a seven-figure asset purchase paired with a mid-six-figure conversion budget (~46% of acquisition basis).
Building a Lender-Ready Conversion Breakdown
Capital markets lenders audit every line required to bridge a property from closing day through flag launch. We assembled a 328-page due-diligence compliance file and multi-year operating budgets isolating every conversion driver:
- Modeled the complete conversion stack proportionally alongside purchase basis: core FF&E accounted for roughly 64% of total capex, paired with explicit franchise initiation fees, prior-flag termination reserves, new monument signage, and PMS hardware allowances.
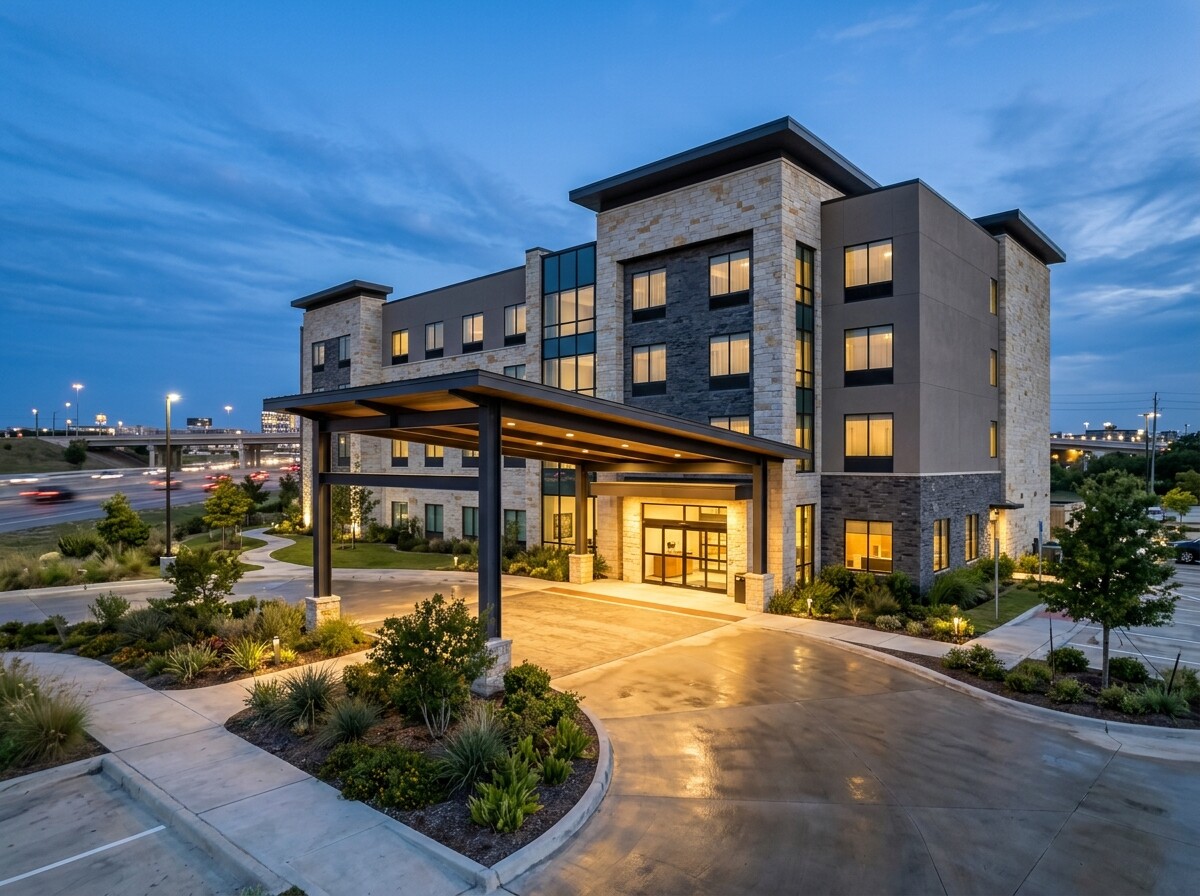
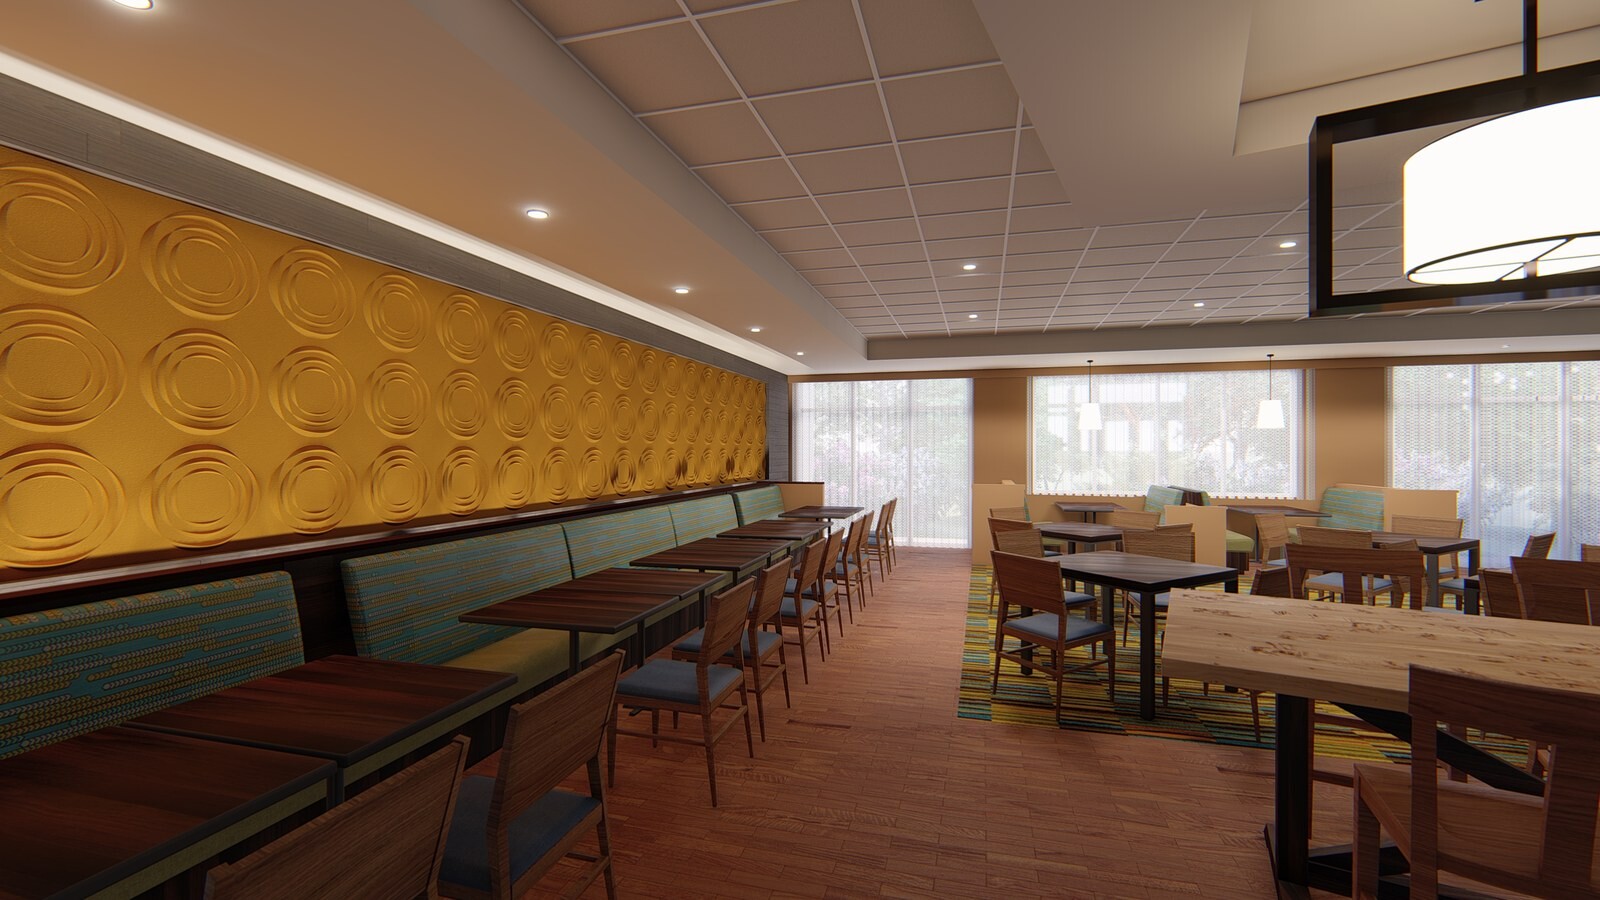
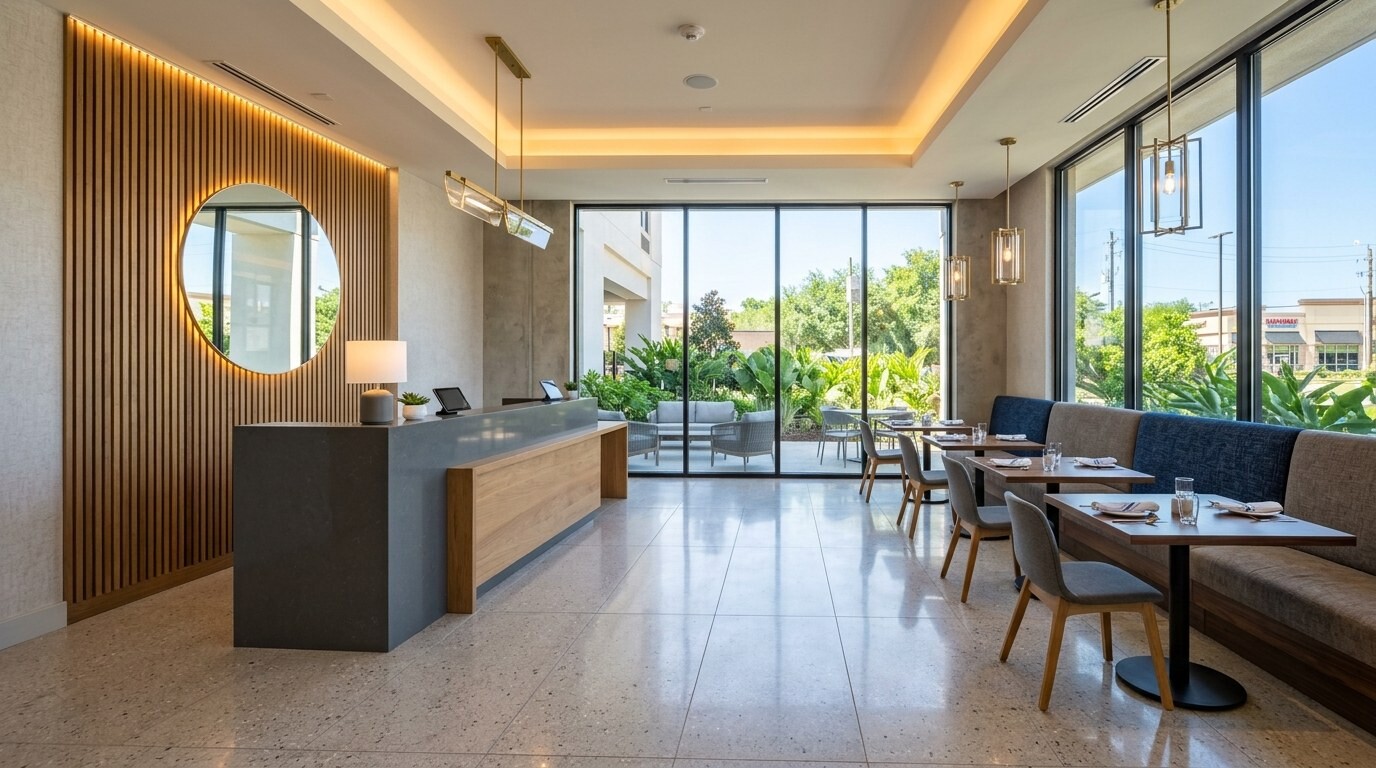
- Scoped soft goods, breakfast area and lobby refreshes, exterior facade upgrades, carpet replacement, interior room prep, legal fees, and closing costs inside one unified uses-of-funds model.
- Reconciled historical bank statement totals against Year 1, Year 2, and Year 3 pro forma budgets to defend debt service coverage during the renovation ramp.
Seeing the Physical Plant Like a Credit Committee
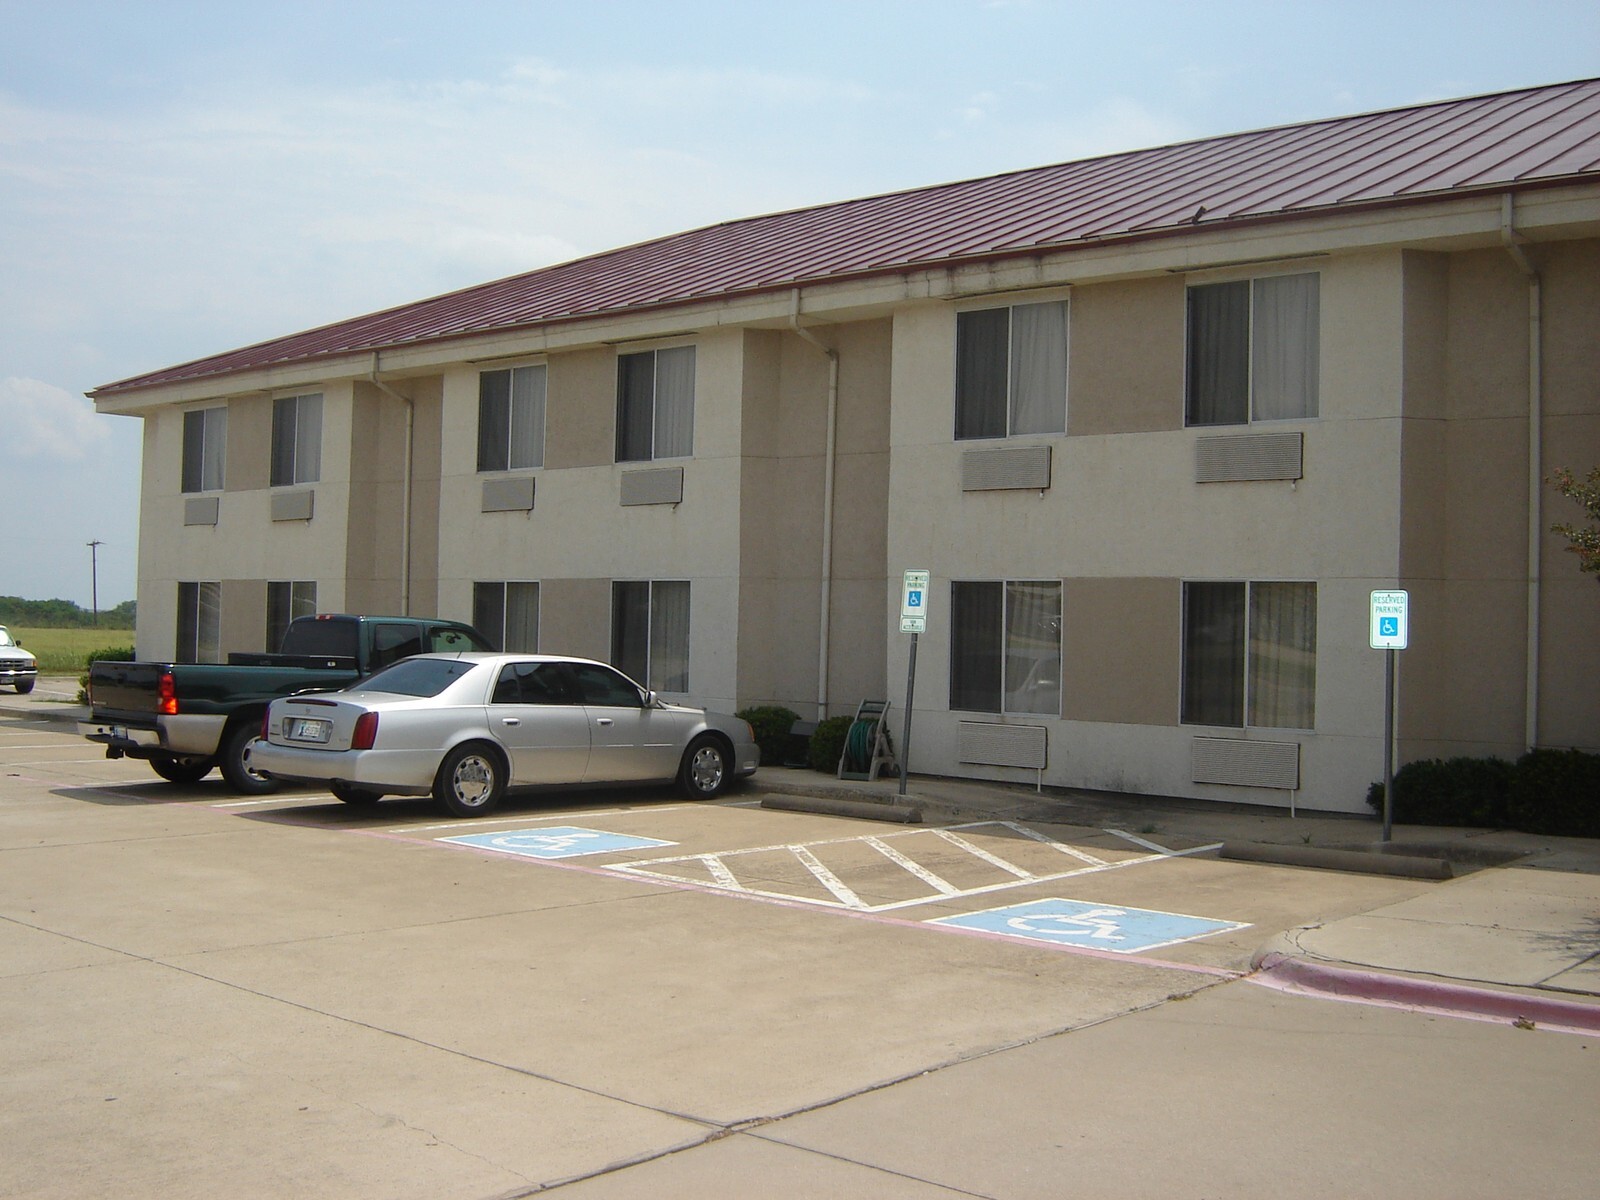
Exterior collateral inspections across the two-story stucco envelope, standing-seam metal roof, PTAC sleeves, and ADA concrete parking validated that structural bones were clean before committing loan application deposits.
The Takeaway
Hospitality deals close when the physical scope speaks the lender's language. Packaging capex ratios, franchise exit costs, and three-year operating budgets upfront clears underwriting friction.